Updated on 14 September 2026.
Morocco mortgage rates in September 2026: rates, payments and real cost
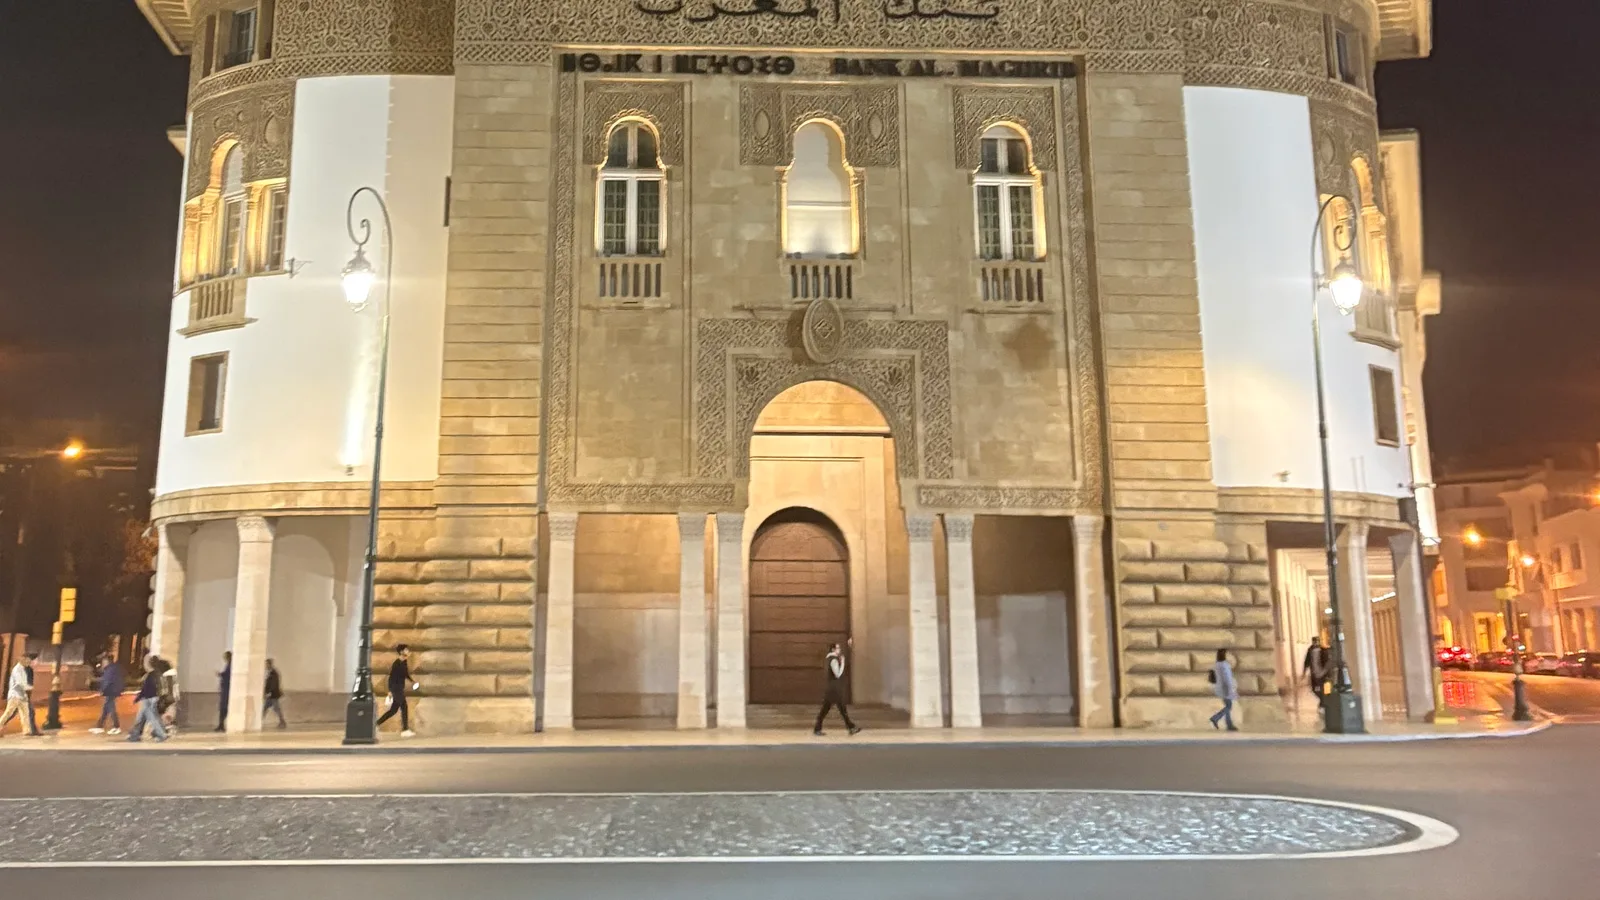
Bank Al-Maghrib is the official reference for lending-rate surveys, while brokers and banks show the dispersion by borrower profile. In mid-2026, public market reporting pointed to mortgage rates around 4% for the strongest profiles, with broad ranges closer to 4.5%–5.5% depending on bank, duration, income stability, down payment and insurance.
| Loan amount | 15 years | 20 years | 25 years |
|---|---|---|---|
| 500 000 DH | 3 875 DH | 3 330 DH | 3 055 DH |
| 1 000 000 DH | 7 750 DH | 6 660 DH | 6 110 DH |
| 1 500 000 DH | 11 625 DH | 9 990 DH | 9 165 DH |
| 2 000 000 DH | 15 500 DH | 13 320 DH | 12 220 DH |
Fixed or variable, and what changes the real cost
The headline rate is not the full cost. A buyer must add insurance, file fees, notary and registration costs, valuation, possible mortgage fees and the opportunity cost of the down payment. Longer duration lowers the monthly payment but increases total interest. A borrower can qualify for credit while the underlying property remains a weak investment. That is why the S.A.F.E property-analysis framework separates financing capacity from property quality.
Source distinction
Official data: Bank Al-Maghrib rate surveys and monetary-policy context. Market data: broker and bank indications. Simulations: editorial calculations, not binding offers.
Reading a bank offer
Compare the nominal rate, APR, death-disability insurance, file fees, early-repayment penalties, duration, guarantees and total cost. Two offers with the same headline rate can cost different amounts if insurance or fees differ. Always request an amortisation table.
Down payment, duration and debt ratio
The down payment protects both bank and buyer. A longer duration lowers the monthly payment but increases interest. The debt ratio must remain compatible with real income, including service charges, tax, maintenance and vacancy if the asset is rented.
How to use these figures without misreading them
The first mistake is to treat a range as an absolute truth. Official data, property listings, agency observations and bank simulations do not answer the same question. Official data describes registered market activity; a listing shows a seller’s or landlord’s asking position; a banking simulation gives an order of magnitude; field observations help with negotiation. A sound decision puts each source in its proper place.
Start with the use case: main home, second home, rental investment, family purchase, MRE purchase or long-term wealth asset. The same price can be reasonable for one use and excessive for another. Then isolate the total cost: price, acquisition fees, furniture, works, service charges, taxes, vacancy, financing, insurance, management and safety margin.
Checks before signing
- Request documents before discussing yield.
- Compare the price with genuinely comparable assets.
- Reject oral promises that are not written down.
- Check the consistency of advertised area, usable area and plans.
- Anticipate post-purchase costs: co-ownership, maintenance, tax, furniture and vacancy.
- Have major commitments reviewed by the relevant professional.
Warning signs
A price “valid only today”, a guaranteed return without details, refusal to provide documents, a vague delivery calendar, a seller who downplays costs or a pitch based only on 2030 should slow the decision. In Moroccan property, risk often sits in details: incomplete title, missing authorisation, misunderstood surface area, ignored charges or poorly documented payment.
Total credit cost: why duration changes the decision
The monthly payment is only one part of the mortgage decision. With the same rate, extending a loan from 15 to 25 years reduces the monthly pressure but increases total interest. Using the article’s illustrative 4.8% excluding insurance assumption, a 1,000,000 DH loan costs roughly 395,000 DH in interest over 15 years, 598,000 DH over 20 years and 833,000 DH over 25 years. The exact amount changes with the bank offer, insurance and disbursement schedule, but the trade-off is clear.
| Loan | Duration | Simulated payment | Approx. interest excl. insurance |
|---|---|---|---|
| 500,000 DH | 15 years | 3,875 DH | 197,500 DH |
| 500,000 DH | 25 years | 3,055 DH | 416,500 DH |
| 1,000,000 DH | 15 years | 7,750 DH | 395,000 DH |
| 1,000,000 DH | 25 years | 6,110 DH | 833,000 DH |
A buyer should request the full amortisation table, total amount due, insurance cost, early-repayment rules and bank fees. A low headline rate may be less attractive if insurance or penalties are high.
Down payment, fees and investment stress test
The property budget includes acquisition costs, bank fees, insurance, possible mortgage registration, works, furniture and cash reserve. For investment property, the mortgage must be tested against realistic rent, vacancy, tax, service charges and maintenance. If the asset is in Marrakech, compare the financing plan with current Marrakech rents and not only with optimistic Airbnb revenue.
Questions to ask the bank
Ask for written answers on the nominal rate, full cost, insurance, file fees, early-repayment rules, guarantees and offer validity. Check whether the rate depends on salary domiciliation, a banking package or group insurance. For MRE or non-resident buyers, the bank may request extra income proof, tax documents, bank statements, translations or transfer evidence, so the calendar can be longer.
For rental investment, bank approval is not enough. A monthly payment of 7,750 DH is manageable only if the asset produces enough net income or the buyer accepts a monthly cash contribution. Test the mortgage against long-term rent, short-term-rental execution risk, service charges and resale liquidity before signing.
Final check before accepting a loan
Before accepting a mortgage offer, read it as a long-term commitment. Check that the amortisation table matches the real borrowed amount, that insurance is included in the monthly budget, that file fees are priced, that the term is realistic for your age and that early-repayment rules are written. A low headline rate can be offset by expensive insurance or mandatory banking packages.
Test the loan with a safety margin: service charges, municipal tax, maintenance, small repairs, travel and cash reserve. For investment, run the numbers with lower rent and vacancy. If the balance works only in the best scenario, the risk is not the rate but the whole structure.
FAQ
Are the figures official?
Official indicators are separated from private market estimates and simulations. Listing ranges are not notarized transaction prices.
Should a buyer decide only on yield?
No. Yield must be tested with costs, tax, vacancy, property quality and resale potential.
Keywords
Disclaimer : This article is editorial analysis and does not constitute financial, legal or tax advice. Any investment decision should be preceded by consultation with qualified professionals.